
SemiAnalysis talk about SpaceX’s 10 GW AI compute ambitions. SpaceX can fund the build, they have the power for it, they have the sites and they will get the chips. The Frontier labs [Anthropic, OpenAI and Microsoft] can generate ~$100 million of revenue per megawatt per year today on API inference with GB300-class systems.
Cost of the underlying compute is roughly $12–15 million per MW with 5-year infrastructure-as-a-service averages from providers like CoreWeave, Oracle, Nebius, or self-build economics. This supports ~85%+ gross margins (a blend that includes older/less-performant GPUs. Newer -Rubin chips look even stronger. Revenue per MW rises further with GB300 vs. GB200. They modeled ~$73M to ~$100M under certain assumptions and will improve again with Vera Rubin in 2027.
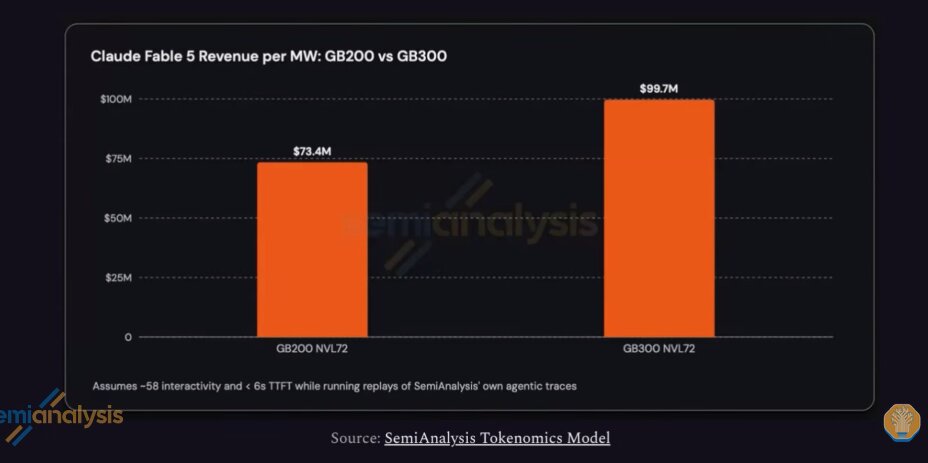
SpaceX is expected to deploy the latest generation. Because no one else is bringing capacity online this quickly, SpaceX can charge a substantial premium (~$50M per MW per year) while still leaving customers with strong margins. Elon recognized the opportunity early and is scaling the emergency megawatts available immediately playbook. If the $100M/MW thesis holds, downstream challenges become more manageable.
The Google deal is cited as an example of significant premium pricing of ~$14/hour vs. a more typical ~$3/hour for a GB300. This is justified by uniqueness, speed-to-power, and a 90-day cancellation clause that gives the buyer near-zero risk. Buyer can walk if economics change. This is framed as emergency megawatts.Inference performance data provides a lower-bound proxy from large open-source models and an upper-bound from hardware-traced frontier shapes, supporting the high revenue-per-MW figures. SpaceX/Google economics imply the buyer expects strong returns. Leaked lab financials showing ~85% margins align with the models.
Semianalysis thinks the risk is whether SpaceX can actually deliver the capacity (sites, power, labor, equipment, financing). Semianalysis feels the demand exists at those prices at least for a few years. Current contracts already cover a portion of existing capacity at high rates.
The Semianalysis team scanned permits and sites extensively. They looked through a million land and site records in a short period. They identified viable candidates including several large warehouses (~800k–1M+ sq ft, potentially supporting 0.5–1+ GW each based on density comparisons to existing Macro/Colossus-style sites and sites with emerging gas pipelines. Liens and other records also surfaced candidates linked to related entities.
They identified at least 7 gigawatts or available turbines that SpaceX can access in 2027. These were on the secondary market. Elon already has 9-10 gigawatts of energy on order or available.
They also checked labor, cooling equipment and switch gear. Elon is able to get things done with a factor of 3-4X less people than others. He can get things pre-manufactured from China.
SpaceX will use a lot of equipment that is available from China.
Permitting Playbook
Unconventional and pragmatic. Mississippi/Colossus 2 example data center near the Tennessee border. Power plant permitted across the border. Mobile turbines rolled in beyond initial allowances, eventually totaling dozens (69 referenced). DOJ ultimately intervened in a way that allowed continuation. Warehouses are often already zoned/permitted, allowing faster conversion (rip out and install) with mainly air permits needed for generation. Power plants can be sited miles away with private transmission. He did it with medium voltage which is inefficient.
Microsoft’s Role
Only a handful of entities (OpenAI, Microsoft via OpenAI IP/access, Anthropic) can fully monetize frontier models at the ~$100M/MW level without revenue-share drag. Microsoft is well-positioned but faces capacity gaps.
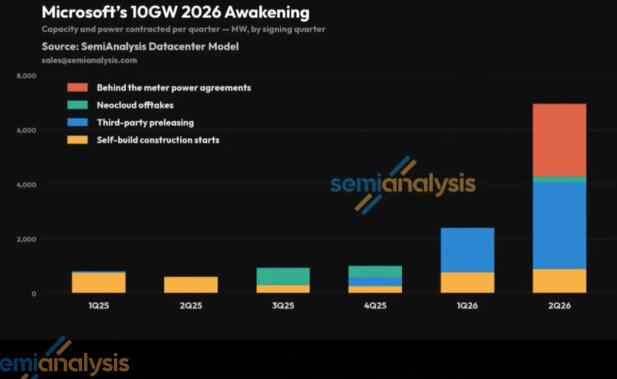
Microsoft paused aggressive data-center expansion in late 2024/early 2025. They have a large offtake commitment to OpenAI. This is about ~7 GW, largely as lower-margin infrastructure-as-a-service ~$12–14M/MW rather than high-margin token sales.
Microsoft signed pre-leasing ~7 GW YTD. Self-build acceleration at sites like Fairwater, NeoCloud deals, new behind-the-meter agreements such as ~2.7 GW with Chevron in Pecos County will mostly deliver in late 2027–2028. This leaves a near-term hole in late 2026/H1 2027.
Paying For It
Existing contracts on a portion of current capacity (~1–1.5 GW of the ~2 GW trajectory) already generate high annualized revenue (~$50B referenced) at very high margins (90%+ EBITDA-like). Scaling to 10 GW with meaningful external monetization at $50M/MW produces enormous operating cash flow). GPUs pay back in under a year at these rates, enabling vendor financing.
Brian Wang is a Futurist Thought Leader and a popular Science blogger with 1 million readers per month. His blog Nextbigfuture.com is ranked #1 Science News Blog. It covers many disruptive technology and trends including Space, Robotics, Artificial Intelligence, Medicine, Anti-aging Biotechnology, and Nanotechnology.
Known for identifying cutting edge technologies, he is currently a Co-Founder of a startup and fundraiser for high potential early-stage companies. He is the Head of Research for Allocations for deep technology investments and an Angel Investor at Space Angels.
A frequent speaker at corporations, he has been a TEDx speaker, a Singularity University speaker and guest at numerous interviews for radio and podcasts. He is open to public speaking and advising engagements.