
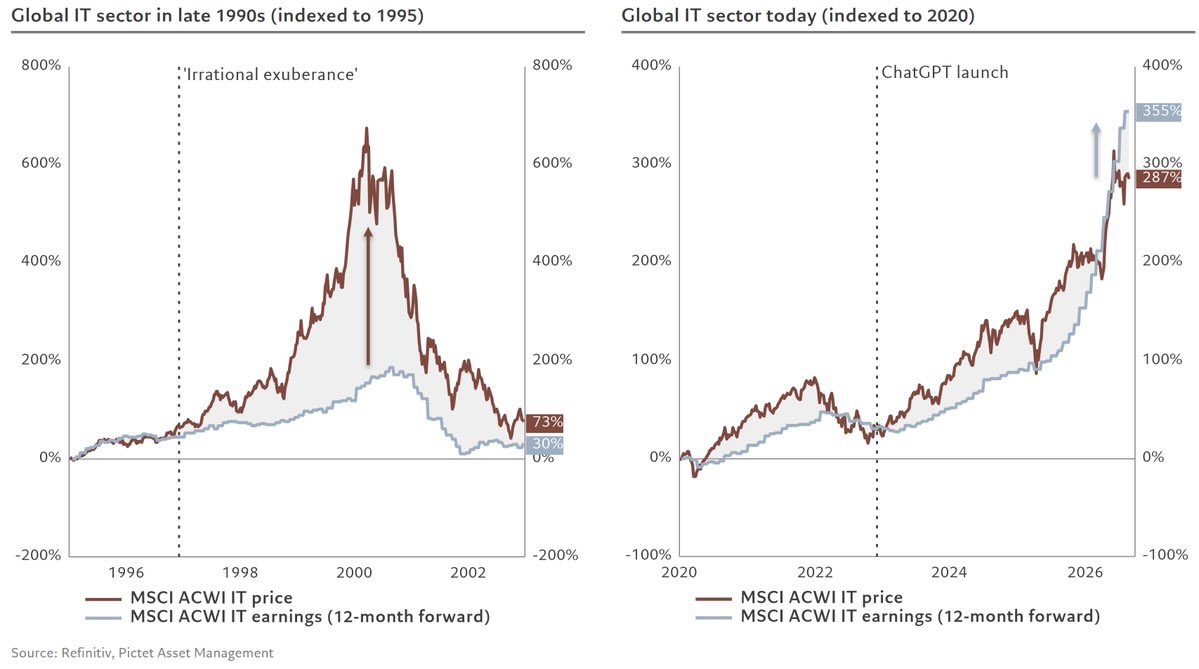
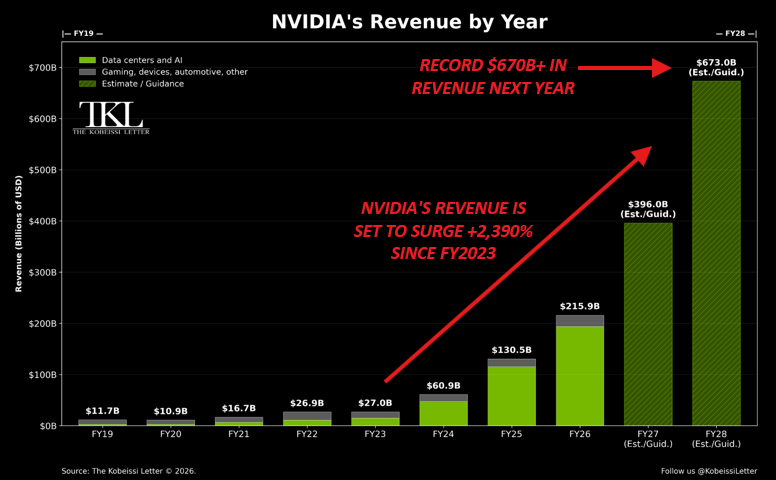
Raymond James analyst Simon Leopold says Nvidia could make $1 trillion in revenue for the fiscal year that ends in January 2029. At yesterdays earnings call, Nvidia guided to 70% revenue growth for 2027. Nvidia is likely to make 403 billion in revenue in 2027. 70% growth would hit almost $700 billion in 2028. They said they could have hit $800 billion but have some supply chain issues.
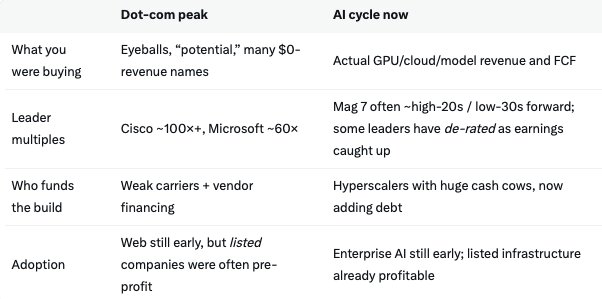
A plausible short term AI bust window is therefore not “when AI is mature.” It is when one or more of these flip.
Hyperscaler capex growth goes from +70–80% to flat or down
Incremental AI revenue no longer covers incremental depreciation
Financing costs (bond spreads, private credit, residual-value assumptions on 3–5 year GPUs vs 10–20 year bonds) stop playing along
Model improvement stalls enough that open-source / “good enough” kills token pricing
We saw 30-50% share pullbacks this year in some of the AI names.
Overbuild signals
Spot prices fall while shipments are still strong.
GPU rental rates, HBM, high-layer PCBs, power equipment lead times all ease together.
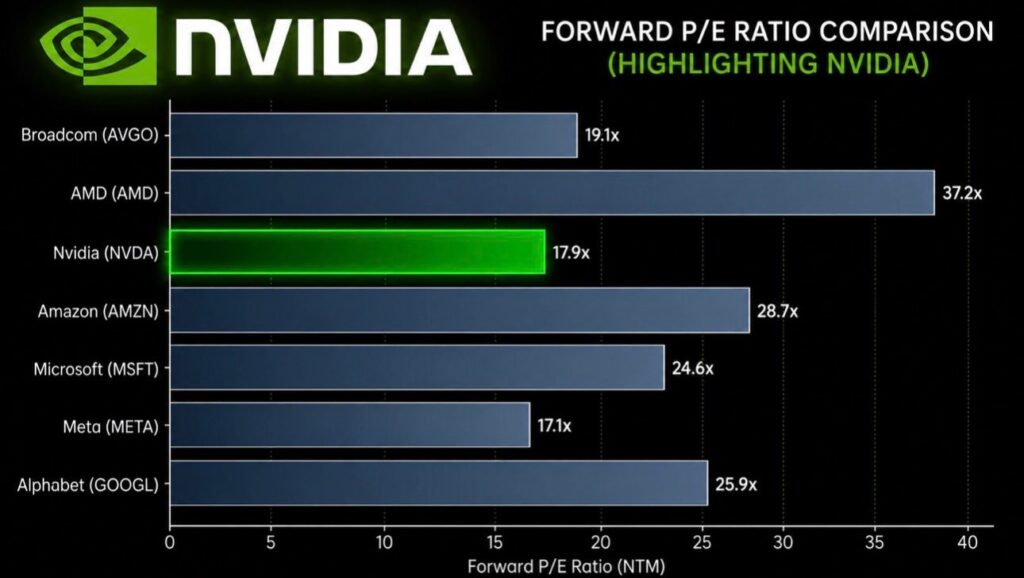
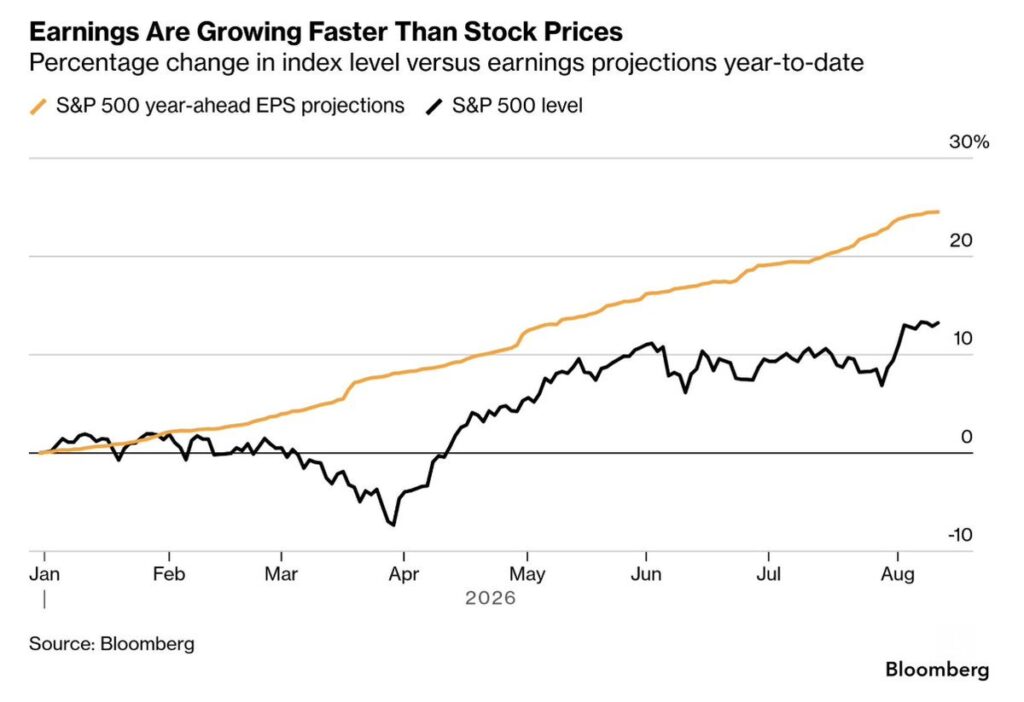
If earnings keep beating and supply stays the bottleneck, pullbacks are 1987/2022-style multiple events. You buy the strong companies on the pullback.
Crashes where earnings kept growing
The de-rating crash is a distinct species from the earnings-collapse crash:
Nifty Fifty, 1973–74. Coca-Cola, Xerox, Polaroid, IBM. Aggregate earnings for the group kept rising through the decade. The stocks fell 50–80% because the multiple went from ~42x to ~9x. Nothing broke operationally. The discount rate broke.
1968–1982. S&P 500 nominal earnings roughly tripled. The index went nowhere for 14 years.
Microsoft, 2000–2014. EPS up roughly 4x. The stock did not regain its 1999 high until late 2016. Cisco’s earnings eventually exceeded 2000 levels; the stock still hasn’t.
Nvidia, 2022. Down 66% peak to trough while data center revenue was still growing.
IF capex deceleration is combined with revenue still accelerating then the market is healthy. If Capex is still accelerating while revenue growth decelerates then this is a bust setup.
With aging in Japan, Korea, China, and Europe makes labor-substituting technology more valuable, not less. If AI genuinely substitutes for scarce labor, the payback period in shrinking-workforce economies is shorter than simple TAM model implies. This is the strongest version of the adoption S-curve is early.
Brian Wang is a Futurist Thought Leader and a popular Science blogger with 1 million readers per month. His blog Nextbigfuture.com is ranked #1 Science News Blog. It covers many disruptive technology and trends including Space, Robotics, Artificial Intelligence, Medicine, Anti-aging Biotechnology, and Nanotechnology.
Known for identifying cutting edge technologies, he is currently a Co-Founder of a startup and fundraiser for high potential early-stage companies. He is the Head of Research for Allocations for deep technology investments and an Angel Investor at Space Angels.
A frequent speaker at corporations, he has been a TEDx speaker, a Singularity University speaker and guest at numerous interviews for radio and podcasts. He is open to public speaking and advising engagements.
For a completely different perspective. see:
https://www.youtube.com/watch?v=Lf5oqGOCRCM;
The Man Who Calls BS On AI: They’re LYING About AI, 2027 Is When It All Breaks! | Ed Zitron
My take:
The AI revolution is fundamentally real, yet its current corporate architects are profoundly overvalued, floating on a dangerous sea of market hype.
While we must remain fiercely skeptical of the unsustainable financial bubble fueling today’s tech sector, the underlying shift is entirely structural.
Ultimately, once the inevitable economic correction clears, this relentless push towards autonomous artificial intelligence and accompanying infrastructure will either catalyze the most sweeping transformation in human history OR orchestrate our violent obliteration.
1. Keep your eye on when new chip fab construction decelerates.
2. Keep your eye on when new chip fab construction decelerates.
3. Keep your eye on when new chip fab construction decelerates.
This is a great reminder of how long it can take a market to recognize the earnings situation.
This is a great line, “IF capex deceleration is combined with revenue still accelerating then the market is healthy. If Capex is still accelerating while revenue growth decelerates then this is a bust setup.”
I’m watching like a hawk for any signs of supply catching up to demand. So far I don’t see it. I see the opposite.